The information on this website is general in nature and does not take into account your objectives, financial situation, or needs. Consider seeking personal advice from a licensed adviser before acting on any information.
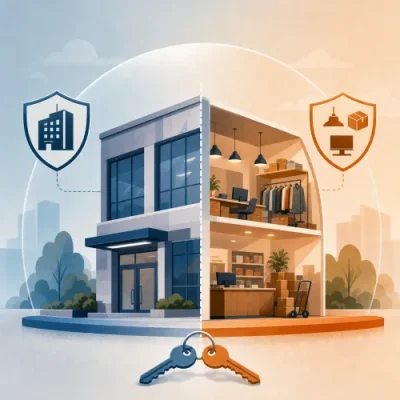
In a leased commercial property, insurance responsibility is usually divided between the landlord, the tenant and sometimes a strata or owners corporation. The lease, property ownership structure and policy wording determine who must insure the building, fit-out, contents, glass, liability risks and income-related losses.
Commercial lease insurance responsibilities can be confusing because the person who owns the building is not always the person using the premises. A landlord may insure the commercial building, while a tenant may need cover for stock, equipment, fit-out, glass, liability and business interruption risks.
The exact position depends on the lease, the property type, ownership structure, insurer requirements and any lender or strata obligations. This article provides general information for Australian commercial landlords, tenants, small business owners and property investors. It is not legal or personal financial advice, and lease documents should be reviewed carefully before arranging cover.
The short answer: the lease usually decides
In most commercial leasing arrangements, the lease is the main document that sets out who must arrange and pay for different types of insurance. It may require one party to hold a policy, name or note another party's interest, provide a certificate of currency, or reimburse insurance costs as part of outgoings.
As a broad guide, landlords often insure the building they own, while tenants often insure the assets and activities they control. However, there are many exceptions. For example, a tenant may be responsible for shopfront glass, internal fit-out or damage they cause, even if the landlord insures the building structure.
If you are new to the topic, the Commercial Property Insurance Online homepage explains commercial property insurance in the Australian market, while this article focuses specifically on how responsibilities may be divided under a lease.
Common commercial lease insurance responsibilities
The table below outlines how responsibility is commonly divided. It is a guide only. The lease wording and policy terms should always be checked.
| Insurance area | Often arranged by | Why it matters |
|---|
| Building insurance | Landlord, owner or strata body | Helps protect the physical structure, such as walls, roof, floors and permanent building services, subject to policy terms. |
| Landlord fixtures and base building items | Landlord | May include permanent fixtures owned by the landlord, depending on the lease and policy wording. |
| Tenant fit-out and improvements | Tenant, landlord or both | Responsibility can depend on who paid for the fit-out, who owns it and whether it becomes part of the building. |
| Business contents, stock and equipment | Tenant | The tenant generally controls and benefits from these assets, so the tenant commonly insures them. |
| Glass, signage and shopfronts | Often tenant, but varies | Many leases place glass or shopfront repair obligations on tenants, especially retail or street-facing premises. |
| Public and product liability | Usually tenant for business operations; landlord for ownership/common areas | Liability risks can arise from both property ownership and the tenant's business activities. |
| Loss of rent | Landlord | May help protect rental income if an insured event prevents the property being leased or occupied. |
| Business interruption | Tenant | May help a tenant manage income loss and extra costs after an insured event affects business operations. |
Who usually insures the commercial building?
The owner of the commercial building will usually have the main interest in insuring the building itself. This may be an individual landlord, company, trust, property investor, lender-controlled structure or strata body, depending on how the property is owned.
Commercial building insurance may cover insured damage to the building from events such as fire, storm, impact, malicious damage or other insured risks, subject to exclusions, limits and conditions. To understand the broader types of cover that may be available, see What does Commercial Property Insurance cover?.
In some leases, the landlord arranges the building insurance and then recovers the cost from the tenant as part of outgoings. This does not necessarily mean the tenant controls the policy or can claim under it directly. The lease should clarify whether insurance premiums can be recovered and how evidence of insurance is provided.
What does the tenant usually insure?
Tenants commonly need to insure the assets they bring into the premises and the risks created by their business activities. This may include:
- stock and inventory, such as retail products, raw materials or finished goods;
- business contents, including furniture, computers, tools, machinery and movable equipment;
- tenant fit-out, such as counters, shelving, flooring, partitions, display areas or kitchen installations;
- public liability for injury or property damage connected with the tenant's business operations;
- product liability where the tenant sells, supplies or manufactures goods;
- business interruption, where available and appropriate, for interruption to trading after an insured event;
- glass and signage if the lease makes the tenant responsible for repair or replacement.
Some tenants assume the landlord's building policy will also protect their business assets. This is often not the case. A landlord's commercial property policy generally focuses on the landlord's insurable interest, while a tenant's policy needs to respond to the tenant's own assets and liabilities.
Tenant fit-out insurance can be especially unclear
Tenant fit-out insurance is one of the most common areas of confusion in a commercial lease. Fit-out may include items that are physically attached to the premises, but that does not automatically mean the landlord insures them.
Responsibility may depend on questions such as:
- Who paid for the fit-out?
- Does the lease say the fit-out becomes the landlord's property once installed?
- Is the tenant required to remove the fit-out at the end of the lease?
- Does the landlord's building policy include tenant improvements?
- Does the tenant's business insurance include fixtures, fittings and improvements?
- Are there separate limits for fit-out, plant or equipment?
For example, a café tenant may install counters, seating, refrigeration, kitchen equipment and floor finishes. Some items may be movable business equipment, while others may be fixed improvements. The insurance responsibility may not be obvious unless the lease and policy schedules are read together.
Public liability: landlord and tenant risks are different
Public liability is another area where both parties may need cover, but for different reasons. A landlord may need liability cover connected with property ownership, common areas or landlord-controlled maintenance. A tenant may need liability cover connected with customers, suppliers, staff interactions, products, services and day-to-day business activity.
A lease may require the tenant to hold a minimum level of public liability insurance and provide a certificate of currency before taking possession. It may also require the landlord to be noted as an interested party. These requirements are common commercial risk controls, but the details vary between leases and insurers.
Being named, noted or listed on a policy does not always give the same protection as being an insured party. If this wording matters, it should be checked with the insurer, broker or a legal adviser.
Glass, shopfronts, signs and external fixtures
Commercial leases, particularly retail leases, may make tenants responsible for plate glass, shopfront glazing, doors, signs, awnings or external fixtures. This can surprise tenants who assume these items form part of the building.
The practical question is not only who owns the item, but who must repair or replace it if it is damaged. A lease may place repair obligations on the tenant even where the item is physically attached to the building. Tenants should check whether their policy includes glass cover or whether it must be added separately.
Loss of rent versus business interruption
Loss of rent and business interruption are related but not the same.
Loss of rent is usually a landlord concern. It may help protect rental income if an insured event damages the property and prevents the tenant from occupying it or paying rent, subject to the policy terms.
Business interruption is usually a tenant concern. It may help with lost income, increased costs of working or other covered interruption costs if the tenant's business cannot operate normally after an insured event, again subject to policy terms and limits.
The lease may also set out whether rent is abated, suspended or still payable after damage to the premises. Insurance should be considered alongside those lease provisions, because a gap between the lease and the policy can create financial pressure for either party.
What if the property is strata titled?
In a strata-titled commercial property, building insurance may be arranged by the owners corporation or body corporate rather than by an individual landlord. This can affect who insures the building structure, common property and shared services.
However, strata insurance may not cover everything a landlord or tenant expects. It may exclude tenant contents, business stock, certain improvements, loss of rent, machinery, signs or liability connected with business operations. Landlords and tenants should check the strata policy, lease and their own policies for gaps or overlaps.
Are tenants legally required to have commercial property insurance?
Commercial property insurance is not automatically mandatory for every Australian business in every situation. However, a lease, lender, landlord, franchisor, supplier contract or industry arrangement may require particular insurance before a tenant can occupy or trade from the premises.
For a broader discussion of when cover may or may not be required, see Is Commercial Property Insurance Mandatory for Businesses?. Landlords can also review Is Commercial Property Insurance Mandatory? What Every Landlord Should Know for landlord-specific considerations.
Even when insurance is not strictly compulsory, the financial consequences of uninsured property damage, liability claims or business interruption can be significant. The right approach depends on the property, business activity, lease obligations and each party's risk tolerance.
How leases may allocate insurance costs
A lease may separate the obligation to arrange insurance from the obligation to pay for it. For example, a landlord may arrange building insurance but recover the premium from the tenant as an outgoing. Alternatively, a tenant may arrange specified insurance at its own cost and provide proof to the landlord.
Common lease provisions may deal with:
- which policies each party must hold;
- minimum sums insured or liability limits;
- whether a policy must note the other party's interest;
- how often certificates of currency must be provided;
- whether the landlord can recover insurance premiums as outgoings;
- what happens if one party fails to maintain required cover;
- who pays any excess after a claim;
- whether cover must include specific risks such as glass, flood, machinery breakdown or loss of rent.
Insurance cost recovery can be sensitive, particularly in retail leasing and small business tenancies. The relevant lease, state or territory rules and professional advice should be considered before signing or disputing an obligation.
Questions to ask before signing or renewing a lease
Before entering or renewing a commercial lease, landlords and tenants should clarify insurance responsibilities in writing. Useful questions include:
- Who insures the building structure?
- Who insures landlord fixtures and base building services?
- Who insures tenant fit-out, improvements, stock and equipment?
- Who is responsible for glass, signage, awnings and shopfronts?
- What public liability insurance must the tenant hold?
- Does the landlord need to be noted on the tenant's policy?
- Can the landlord recover building insurance premiums as outgoings?
- Who pays the policy excess if damage is caused by the tenant, landlord or a third party?
- Does either party need loss of rent or business interruption cover?
- Are flood, storm, fire, theft, malicious damage or machinery risks treated differently?
- Is the property strata titled, and what does the strata policy actually cover?
- What evidence of insurance must be provided, and how often?
Where the lease is complex, the premises have a high-value fit-out or multiple parties have interests in the property, it may be useful to speak with an insurance broker through the Brokers page and obtain legal advice on the lease wording.
Common gaps and overlaps to watch for
Insurance arrangements can fail when the lease and the policies do not line up. Common issues include:
- Assuming the landlord's policy covers tenant assets: tenant stock, contents and equipment often need separate cover.
- Overlooking fit-out ownership: if neither party clearly insures improvements, a damage claim may become difficult.
- Ignoring glass obligations: tenants may be responsible for shopfront glass without having arranged glass cover.
- Duplicating cover without coordination: two policies may appear to cover the same item, but exclusions and contribution clauses can complicate claims.
- Missing business interruption: property damage cover alone may not protect ongoing operating costs or lost revenue.
- Not reviewing policy limits: sums insured and sub-limits may be insufficient if fit-out, stock or machinery values increase.
- Forgetting lease updates: new lease terms, rent increases, refurbishment or changes in use may affect insurance needs.
Some optional add-ons may be relevant depending on the property and business activity. For more on extensions that may be considered beyond basic property cover, see Beyond the Basics: Essential Add-Ons for Comprehensive Commercial Property Insurance.
How landlords and tenants can coordinate cover
Good coordination reduces the chance of disputes when something goes wrong. Landlords and tenants can take practical steps such as:
- Review the lease before arranging cover. Identify each insurance obligation, including who pays, who arranges cover and who must provide evidence.
- Compare the lease with policy wording. A lease obligation is not the same as insurance cover. The policy must actually respond to the risk.
- Keep certificates of currency current. If the lease requires evidence, diarise renewal dates and provide updated documents promptly.
- Document ownership of fit-out and equipment. Keep invoices, asset registers, photos and fit-out plans where possible.
- Notify insurers about changes. Renovations, new tenants, changed business activities, vacancy or increased stock values may affect cover.
- Agree on claim communication. After damage, both parties may need to coordinate access, repairs, evidence, rent issues and insurer inspections.
Key takeaway
In a commercial lease, insurance responsibility is usually split according to ownership, control and lease obligations. Landlords commonly insure the building and rental income risks, while tenants commonly insure their contents, stock, fit-out, business interruption and operational liability. However, items such as glass, signage, fit-out and liability can vary significantly.
The safest approach is to read the lease, check the relevant policies and confirm responsibilities before signing, renewing or making changes to the premises. Where obligations are unclear, seek professional legal and insurance guidance rather than relying on assumptions.
Published: Wednesday, 19th Aug 2026
Author: Paige Estritori


We got caught on shopfront glass in our last lease, so I’d definitely check that clause before assuming the landlord’s policy covers it.