The information on this website is general in nature and does not take into account your objectives, financial situation, or needs. Consider seeking personal advice from a licensed adviser before acting on any information.
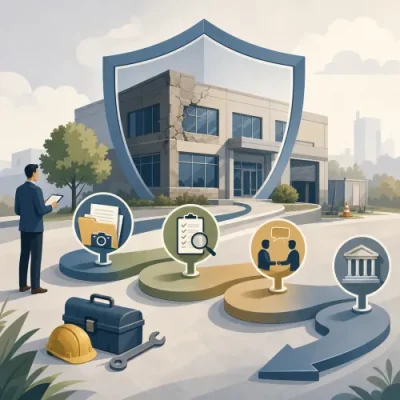
If a commercial property insurance claim is delayed, disputed or declined, policyholders can take practical steps to clarify the insurer's position, strengthen their evidence, use the insurer's internal dispute resolution process and, where eligible, escalate the complaint to AFCA.
A delayed or declined commercial property insurance claim can create significant pressure for property owners, landlords and business operators. Repairs may be on hold, tenants may be affected and cash flow may be strained while the insurer reviews the claim.
This guide explains practical steps Australian policyholders can take when a claim is taking too long, the insurer disputes part of the loss, or a commercial property insurance claim is denied. It is general information only and does not replace advice based on your policy, claim facts and business circumstances.
Start by confirming what your commercial property insurance policy says
Before challenging a delay or decision, review the documents that apply to your claim. These may include your policy schedule, product disclosure statement, certificate of currency, endorsements, renewal notices and any special conditions agreed with the insurer.
If you need a refresher on the types of protection that may sit within commercial property insurance, it may help to compare your claim against the broad categories of cover first. You can also review what commercial property insurance may cover and exclude so you understand why an insurer may be asking further questions.
Pay particular attention to:
- The insured events: whether the cause of loss is listed or otherwise covered under your policy wording.
- Exclusions: common examples may include wear and tear, gradual deterioration, faulty workmanship, lack of maintenance or specific events not insured by that policy.
- Conditions: obligations to take reasonable steps to prevent further damage, notify the insurer promptly, secure the property and provide requested information.
- Limits and sub-limits: the maximum amount payable for certain property, locations, events or additional benefits.
- Deductibles or excesses: amounts you may need to contribute before a claim payment is made. For more detail, see how deductibles can affect commercial property insurance claims and premiums.
Keep organised evidence from the start
Many claim problems arise because the insurer needs more information before it can decide whether the policy responds. Strong records do not guarantee a claim will be accepted, but they can make it easier to explain what happened and respond to questions.
Useful evidence may include:
- photos and videos of the damage before clean-up or repair, where safe to obtain;
- maintenance records, inspection reports and repair invoices;
- purchase receipts, asset registers and valuation information;
- tenant reports, incident reports or witness details;
- police, fire, emergency service or building reports where relevant;
- quotes, scopes of work and reports from builders, engineers or other specialists;
- a record of business interruption, rent interruption or lost trading periods if those covers are included in your policy.
For claims involving bushfire, storm, flood or other severe weather events, the evidence and timing issues can be more complex. The article on natural disasters and commercial property insurance explains additional considerations for disaster-related claims.
What to do if your claim is delayed
A claim may be delayed for many reasons. The insurer may be waiting for assessor reports, expert opinions, repair quotes, confirmation of ownership, proof of loss, policy records or information from another party. Some delays are unavoidable, but unexplained or repeated delays should be followed up in writing.
Ask for a clear explanation
Contact the claims handler and ask:
- what information is still needed;
- who is responsible for obtaining it;
- what decision or step the insurer is currently considering;
- when you can expect the next update;
- whether any part of the claim can be progressed while another part remains under review.
Ask for the response in writing. This gives you a clear record and can help prevent misunderstandings later.
Check whether you have outstanding obligations
Delays can sometimes occur because the policyholder has not supplied requested documents or has not allowed access for inspection. Review all emails, letters and claim portal messages to check whether the insurer is waiting on you, your tenant, a contractor or another party.
If you cannot provide a document, explain why and ask whether there is an alternative form of evidence the insurer will consider.
Keep a communication log
Record each contact with the insurer, including the date, the person you spoke with, what was discussed and any promised next steps. If you speak by phone, send a short follow-up email confirming your understanding of the conversation.
A communication log is particularly useful if the delay later becomes an insurance claim dispute in Australia and you need to show the steps you have taken to progress the matter.
What to do if your claim is disputed or declined
If your insurer disputes the claim amount, accepts only part of the claim or declines the claim entirely, the first step is to understand the exact reason for the decision.
Request the insurer's reasons in writing
Ask the insurer to identify the specific policy wording, exclusion, condition, limit or factual finding it is relying on. A general statement that the claim is not covered may not give you enough information to respond properly.
The written decision should help you understand whether the issue is about:
- the cause of the damage;
- whether the event is insured;
- an exclusion or policy condition;
- the value of the loss;
- the scope of repairs;
- late notification or alleged non-compliance with policy obligations;
- underinsurance, limits, sub-limits or deductibles;
- misrepresentation or non-disclosure issues from when the policy was arranged or renewed.
Compare the decision with your evidence
Once you know the insurer's reason, compare it with your documents and the policy wording. For example, if the insurer says the damage was caused by gradual deterioration, consider whether there are inspection records, maintenance invoices or expert reports that support a different cause.
If the dispute is about the repair amount, you may need a detailed scope of works or another quote. If the dispute is about causation, a specialist report may be useful. The right evidence depends on the facts of the claim.
Avoid making unsupported statements
When responding to a declined claim, focus on facts, documents and policy wording. Avoid exaggerating the loss or guessing about causes. Inconsistent explanations can create further delays and may weaken your position.
Use internal dispute resolution with the insurer
If informal follow-up does not resolve the issue, you can usually lodge a formal complaint through the insurer's internal dispute resolution insurance process. This is often referred to as IDR.
Internal dispute resolution gives the insurer an opportunity to review the claim decision, delay or conduct before the matter is escalated externally. In Australia, insurers and other financial firms generally have complaint-handling obligations where the product and customer fall within the relevant regulatory framework. The precise process and timeframes can depend on the insurer, the product and the nature of the complaint.
How to lodge an IDR complaint
Your complaint should be clear, organised and specific. Include:
- your policy number and claim number;
- the property address and date of loss;
- a short timeline of the claim so far;
- the decision, delay or conduct you are complaining about;
- why you disagree, with reference to policy wording and evidence where possible;
- copies of key documents, not originals;
- the outcome you are seeking, such as a claim decision, reassessment, payment of an accepted amount, further explanation or correction of an error.
Ask the insurer to confirm that your complaint has been registered under its IDR process and to tell you when you should expect a response.
Example wording for a complaint
You do not need complex legal language. A simple written complaint might say:
I am lodging a formal complaint about the handling of claim number [claim number]. The claim has been delayed since [date] and I have not received a clear explanation of what information is still required. Please review the claim under your internal dispute resolution process and provide a written response explaining the next steps and the expected timeframe.
If the claim has been declined, you might add:
I disagree with the decision dated [date]. Please identify the policy wording relied on and review the attached evidence, which I believe supports cover for the loss.
Escalating to AFCA for eligible insurance complaints
If the insurer's internal dispute resolution process does not resolve the matter, you may be able to escalate the complaint to the Australian Financial Complaints Authority, commonly known as AFCA.
An AFCA insurance complaint is an external dispute resolution option for eligible complaints against participating financial firms, including many insurers. AFCA can consider some general insurance disputes, but not every commercial property insurance complaint will fall within its jurisdiction.
Eligibility can depend on factors such as:
- whether the insurer is covered by AFCA's scheme;
- whether the complainant meets AFCA's consumer or small business eligibility requirements;
- the type of insurance product and dispute;
- the amount in dispute and any compensation limits;
- whether the complaint is lodged within applicable time limits;
- whether the issue has first been raised with the insurer through IDR.
If AFCA accepts the complaint, it may try to resolve the dispute through negotiation, conciliation or a decision-making process. Outcomes depend on the facts, the policy, the evidence and AFCA's rules. Escalating a complaint does not guarantee that a claim will be paid.
When to seek help from a broker, claims professional or legal adviser
Some claim issues are straightforward. Others involve large losses, complex policy wording, expert reports, underinsurance, business interruption calculations or allegations about disclosure and compliance. In those situations, professional support may be worth considering.
An insurance broker may help you understand the policy placement, the cover that was arranged and how to communicate with the insurer. If you are considering assistance, you can review the site's broker information as a starting point.
Depending on the dispute, you may also consider a claims preparer, loss assessor, accountant, engineer, builder, quantity surveyor or legal adviser. Fees, conflicts of interest and the scope of assistance should be discussed before engaging anyone.
Common reasons commercial property claims are declined
Understanding why claims are often declined can help you decide what evidence to gather and what questions to ask. Common issues include:
| Issue |
Why it matters |
Possible response |
| Policy exclusion |
The insurer says the cause of loss is excluded. |
Ask for the exact wording and consider whether the evidence supports a covered cause instead. |
| Insufficient evidence |
The insurer cannot verify the damage, ownership, cause or amount claimed. |
Provide photos, invoices, reports, valuations, maintenance records or other relevant documents. |
| Late notification |
The insurer says the delay affected its ability to assess the claim. |
Explain when you became aware of the loss and why any delay occurred. |
| Maintenance or wear and tear |
The insurer says the damage was gradual rather than sudden or accidental. |
Provide maintenance history, inspection records or expert opinions if available. |
| Deductible, limit or sub-limit |
The claim may be reduced or not payable because of policy limits or excesses. |
Check the policy schedule and ask the insurer to explain the calculation. |
| Disclosure or misrepresentation issue |
The insurer says important information was not provided when cover was arranged or renewed. |
Gather application, renewal and broker correspondence and seek advice if the issue is significant. |
A practical checklist for a delayed, disputed or declined claim
- Read the policy and schedule to identify the relevant cover, exclusions, limits, deductibles and conditions.
- Ask for written reasons for any delay, dispute or decline.
- Confirm what information is outstanding and who is responsible for providing it.
- Organise your evidence in a clear timeline with supporting documents.
- Keep a communication log of calls, emails, inspections and requests.
- Respond promptly to reasonable insurer requests, or explain why you cannot provide the information.
- Lodge a formal IDR complaint if the issue is not resolved informally.
- Consider AFCA if the complaint is eligible and IDR has not resolved the matter.
- Seek professional help where the claim is high value, legally complex or critical to your business continuity.
- Review your cover after the claim to identify gaps, exclusions or documentation practices that may need attention.
After the dispute is resolved
Whether the outcome is payment, partial payment, repair approval, a revised decision or confirmation that the loss is not covered, use the experience to review your insurance arrangements.
Questions to consider include:
- Was the sum insured adequate for the property and improvements?
- Were any exclusions or conditions unexpected?
- Were records easy to access when the claim arose?
- Did tenants, property managers or staff know what to do after the incident?
- Would additional cover, higher limits or different deductibles better suit your risk profile?
Commercial property insurance is not only about arranging cover at renewal. It also involves maintaining the property, keeping records, understanding policy obligations and knowing how to respond if a claim does not progress as expected.
Key takeaways
If a commercial property insurance claim is delayed, disputed or declined, do not rely only on phone conversations or informal updates. Ask for written reasons, check the policy wording, organise your evidence and use the insurer's internal dispute resolution process where needed.
AFCA may provide an external complaint pathway for eligible Australian insurance disputes, but eligibility and outcomes depend on the facts, the policy and AFCA's rules. For complex or high-value claims, consider professional advice before making decisions that could affect your position.
Published: Monday, 24th Mar 2025
Author: Paige Estritori



No comments yet. Be the first to share your thoughts.